
Quick Answer
What should I verify before calculating settlement payoffs?
Identify who claims repayment, the itemized amount, its asserted basis, and whether the figure is interim or final. Confirm fees and costs separately, avoid double counting, and label any reduction used in a calculator as an assumption until resolved.
When a personal injury case settles, several parties may claim part of the money: Medicare, a state Medicaid program, private health plans, or medical providers themselves. Before you or anyone else calculates a net settlement, verify what each claimed balance represents and the date and status of the supporting document. An early figure can change before payoff.
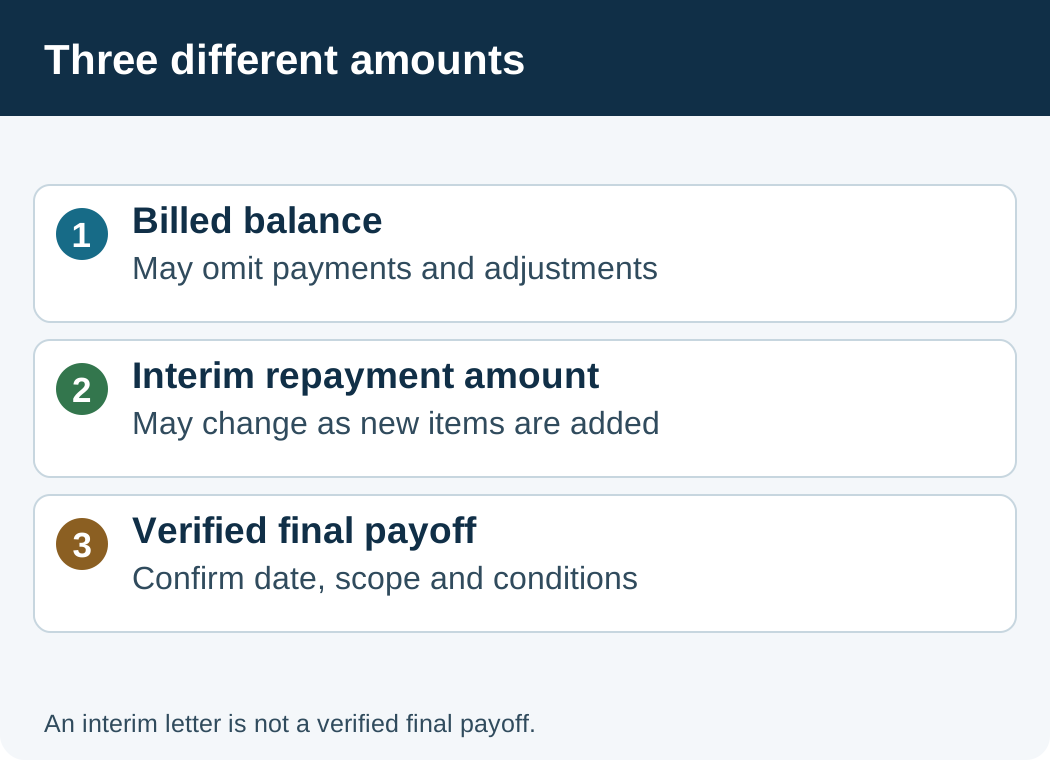
Three different numbers that get confused
It helps to separate three figures that are frequently treated as interchangeable:
- Billed balance. The amount a provider's statement shows. This may not reflect insurance payments, contractual adjustments, or write-offs, and a billed amount is not automatically an enforceable lien.
- Claimed repayment amount. What a payer such as Medicare, Medicaid, or a private plan asserts it is owed. This can change as new claims are processed or disputed items are removed.
- Verified final payoff. The amount stated in a final, current written demand or payoff letter, after disputes and updates. Use current, verified figures when reviewing a final distribution. Earlier estimates can support planning if clearly labeled as assumptions.
Treating a billed balance or an interim claimed amount as the final payoff can distort every downstream number, including attorney fees discussions and the client's expected net recovery.
Medicare: interim versus final amounts
Medicare's recovery process illustrates the difference clearly. According to CMS's conditional payment information page, a Conditional Payment Letter states an interim amount: Medicare may still pay additional claims related to the case after the letter issues, so the total can grow. That page also explains that if the listed claims include items unrelated to the injury, a dispute must be supported by documentation showing why those items should be removed.
Once a case resolves, CMS's reimbursement overview explains that a demand letter contains the repayment amount and information about appeal rights. For demands issued directly to beneficiaries, reasonable procurement costs — the costs of obtaining the settlement — are considered under 42 CFR 411.37. That regulation contains a specific calculation method; the point here is not the math but the sequence: the demand, not an earlier conditional payment letter, states what Medicare is asking to be repaid, and the demand itself explains how to appeal.
Medicaid: state-administered, contract-dependent
Medicaid recovery works differently from Medicare and differently from state to state. As Medicaid.gov's coordination of benefits and third-party liability page explains, Medicaid is generally the payer of last resort: when a third party is legally responsible for medical costs, that party is expected to pay, and states administer the process of identifying and pursuing third-party liability. Where a beneficiary is enrolled in managed care, the plan's responsibilities can depend on the state's contract with that plan. Because the framework is state-administered, the correct contact, the claimed amount, and the resolution process must be confirmed with the specific state agency or plan involved — assumptions carried over from Medicare practice do not transfer.
Providers and private plans
Hospital or provider balances and private health plan reimbursement claims each rest on their own documents: the treatment agreement, any lien filing, the plan document, and whatever law applies to that particular claim. There is no single rule that governs them all. The practical approach is the same as with government payers: request the asserted basis for the claim in writing, an itemized statement, and a current payoff figure. Label any provisional amount used for planning.
Fee agreements belong in the same review
The ABA Model Rule 1.5(c) calls for contingent fee agreements to be in writing and to state the percentage and whether litigation expenses are deducted before or after the fee is calculated. This is a model rule — it does not itself establish the governing rule in every state. Check the applicable state rule and the actual agreement. The before-or-after-expenses question materially changes the net, so read the signed agreement rather than assuming.
Records to verify before final distribution
Keep requests factual and dated, and read the actual notice or demand promptly. Verify its response instructions and the applicable appeal and timing rules; this guide does not calculate those deadlines.
Estimating a net once figures are verified
With verified numbers, an estimating tool such as the medical lien settlement reduction calculator (also available in Spanish) can show how the pieces interact. Its defaults illustrate the mechanics: a $125,000 gross settlement, a 33.3% fee calculated on the gross before $6,500 in costs, and $37,500 in combined medical balances and reimbursement claims ($28,000 plus $9,500). Applying an assumed 25% reduction lowers the combined obligations to $28,125; with the $41,625 fee and costs deducted, the estimated cash to the client is $48,750, versus $39,375 with no reduction — the $9,375 difference equals the balance reduction.
The same tool also shows a harder scenario: at a $10,000 gross with the other inputs unchanged, the fee is $3,330 and estimated cash is $0, leaving a $27,955 shortfall even though the same $9,375 reduction applied. The calculator does not model who absorbs a shortfall, payment priority, or personal debt consequences — those depend on the actual agreements and applicable law. Its reduction input accepts any user assumption from 0 to 100%; it does not suggest permitted fee norms or predict reductions, you must enter each cost and obligation only once, and its generic formula differs from program-specific statutory calculations such as Medicare's.
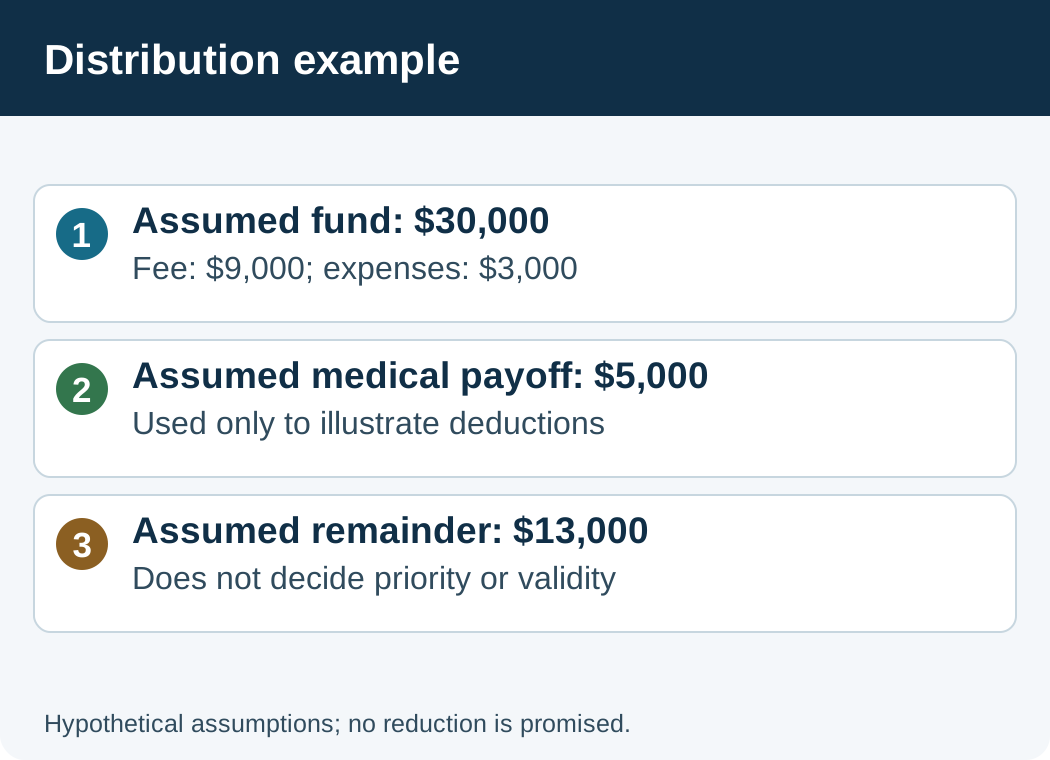
Another example: identified deductions
An assumed $30,000 fund minus an assumed $9,000 fee, $3,000 expenses and a $5,000 medical payoff leaves $13,000. This is an arithmetic comparison with each assumed obligation entered once. It does not reproduce a Medicare formula or establish payment priority, enforceability or approval.
Source scope: The linked CMS, Medicaid and ABA pages were checked on October 2, 2026. The ABA material is a model rule. This guide does not review every state lien statute, private plan, Medicare product or legal exception. It is educational information, not legal advice.

Frequently Asked Questions
Is a Medicare conditional payment letter a final payoff?
How do I dispute unrelated items in a Medicare listing?
Does Medicaid use the same recovery process as Medicare?
Does a reduction always produce more cash?
More Legal Process Guides

Catastrophic Injury Settlements: Life Care Plans & Million-Dollar Claims
Catastrophic injury settlements explained: life care plans, future medical costs, policy limits, liability evidence, and how high-value claims are valued.

Structured Settlements or Lump Sum: Tax and Payment Review
Compare payment timing, liquidity and deductions; separate payment form from tax treatment using IRS sources and an explicit present-value example.

Spinal Cord Injury Lawyer: Compensation & Lifetime Care Guide
Spinal Cord Injury Lawyer: Compensation & Lifetime Care Guide Spinal cord injury lawyer analysis focuses on catastrophic injury litigation, proof of causation, and lifetime care.

Social Security Disability After Injury: Application & Appeals Guide
Social Security Disability After Injury: Application & Appeals Guide social security disability after injury Social security disability after injury analysis focuses on the SSA.

Accident Claim Timeline: Steps, Evidence, and Mistakes
A legal-process accident claim timeline from crash to treatment, records, demand, negotiation, litigation decision, settlement, and release.

Wrongful Termination After Injury: ADA & FMLA Retaliation Claims
Wrongful Termination After Injury: ADA & FMLA Retaliation Claims Wrongful termination after injury cases turn on federal protections under the Americans with Disabilities Act.
Topical Authority Cluster
Authority cluster for damages modeling, liens, structured payouts, and catastrophic-loss planning.
Medical-liens support page tied to net recovery.
Authority Page
Catastrophic Injury Settlements: Life Care Plans & Million-Dollar Claims
Primary authority page on large-loss damages, life-care plans, and major-injury valuation.
Related supporting articles
Structured Settlements or Lump Sum: Tax and Payment Review
Payout-structure support page.
Spinal Cord Injury Lawyer: Compensation & Lifetime Care Guide
Injury-specific catastrophic-loss support page.
Social Security Disability After Injury: Application & Appeals Guide
Benefits coordination support page after serious injury.
Litigation Planning Tools
View all toolsThese worksheets help organize records, deadlines, and claim documents for legal-process and injury-liability topics.
Settlement Demand Letter Organizer Google Sheets
It organizes the numbers, proof, and narrative pieces that sit behind a settlement demand.
Use it when investigation and damages development are far enough along that the file needs a coherent demand package.
Personal Injury Medical Records Tracker Google Sheets
It tracks which records were requested, received, and still missing before the file is reviewed or packaged.
Use it when multiple providers or facilities are involved and records requests are no longer simple to track from memory.
Personal Injury Case Preparation Checklist Google Sheets
It gathers the documents and unanswered questions that usually control whether an attorney can review the file efficiently.
Use it before or just after an attorney consultation, when the issue is turning a loose file into a reviewable intake package.
Personal Injury Statute of Limitations Tracker Google Sheets
It keeps filing and notice dates from drifting when multiple deadlines affect the same matter.
Use it as soon as timing matters and you cannot afford notice, filing, or service deadlines to live in separate calendars.
Guides for this topic

Continue Exploring
Keep moving through the topic with the next guide, the category hub, or a related calculator.
Found this useful?
Share this guide
Send this guide to anyone weighing an accident or insurance claim — it stays free, with no email gate.
Keep learning
Follow for more accident and insurance education
Short legal explainers on TikTok, visual case briefs on Instagram, daily threads on Threads.
Information only — not legal advice.
Editorial Accountability
About this guide and its AI host
JusticeFinder publishes this educational guide. Sophia Hayes is its educational AI host, not a licensed legal professional. Learn about source verification and editorial standards through the JusticeFinder Editorial Team profile and the sources cited in this guide.
- Scope: Educational legal information only, not legal advice
- Last editorial update: October 2, 2026
Sophia Hayes
Educational Accident & Insurance Awareness Host
Sophia Hayes is JusticeFinder's educational AI host and documentary-style narrator covering U.S. accident law, insurance literacy, and public safety. She is not a lawyer, attorney, legal representative, medical professional, or insurance adjuster.
View AI host profile